- Article
- Global Research
- General Research Insights
Can fiscal policy help Australia bring inflation down?
Tighter federal and state fiscal policy would help return inflation to target and reduce the need for further RBA tightening.
Why coordination matters
Fiscal policy covers government choices on tax and spending. It has a major effect on growth and inflation. It can also redistribute income and shape the economy’s productive capacity and productivity.
Monetary policy works differently. It influences demand mainly through the cash rate, a broad rather than targeted tool. Strong coordination between the two policies is therefore preferable.
Politics complicates coordination, helping explain central-bank independence and a clear inflation mandate. In principle, inflation reflects the balance between demand and supply.
The Treasurer-endorsed 2023 RBA review called for better monetary-fiscal coordination. The question is whether that has happened.
Inflation has stayed high
The RBA’s preferred underlying-inflation measure, the trimmed mean, has exceeded the 2.5% target midpoint for four and a half years, suggesting persistent excess demand.
In our view, the RBA cut rates too early and too far in 2025. The US trade shock proved milder than expected, while weak productivity and stronger government spending brought capacity constraints forward.
The limited impact of the Trump tariffs – especially the absence of stronger imported disinflation – also surprised us.
Fiscal policy has added to demand
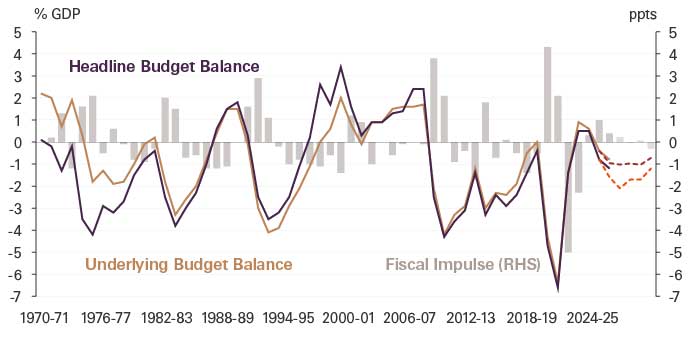
There are two main ways to assess the stance of fiscal policy. Both suggest it has been expansionary and has added to the inflation challenge.
First, the budget balance delivered a positive fiscal impulse last financial year and is expected to do so again this year. Off-budget spending adds further stimulus.
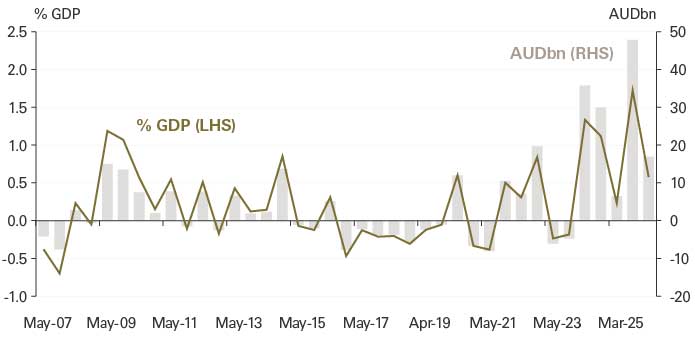
Second, spending beat forecasts in each of the past five six-monthly updates. Recent drivers included the National Disability Insurance Scheme (NDIS), GST payments, home-battery subsidies and disaster relief.
The Parliamentary Budget Office also finds federal and state forecasts too optimistic because expiring programs are often extended or replaced. Overall, the evidence points to expansionary fiscal policy that also surprised the RBA.
Why slower public-demand growth is not enough
Moreover, any rise in public demand still adds to demand in the economy and to inflation pressure. Public demand rose by 2.1% year on year in the second quarter.
Weak productivity lowers the economy’s “speed limit”. If public spending and AI-related data-centre construction keep expanding, households and non-technology businesses must slow for inflation to fall.
What governments could do
In our view, tighter fiscal policy would ease demand and help the RBA return inflation to target. The federal government could use the coming mid-year update to consider further spending cuts.
Priorities include keeping the May-budget NDIS slowdown on track, limiting off-budget spending, subsidies and tax breaks, and restraining public-sector hiring and wages.
Because many pressures are structural, options also include more targeted policy and tax reform, including higher consumption taxes.
States also have a role. New South Wales, for example, has set a debt ceiling of 15% of gross state product and plans to cut debt by AUD10bn.
Without slower spending or higher taxes, the RBA must do most of the work, risking a deeper downturn or recession.
Could the institutions change?
If coordination remains ineffective, institutional reform could help. Strengthening the Charter of Budget Honesty with a goal of balancing the budget over the cycle could complement the RBA’s inflation target. A deficit sits uneasily with full employment, high inflation and high commodity prices—conditions that historically often produced surpluses.
A bigger step would be an independent fiscal authority, an idea we discussed in 2017. It could adjust a cyclical tool such as the GST or superannuation guarantee charge.
Although fiscal policy is often seen as slow, it acted rapidly after the 2008 financial crisis and during COVID-19. New tools could make it faster, more targeted and better able to tighten as well as support the economy.
The budget balance is in deficit with more spending ‘off budget’ too…
Federal Government Budget Balance
...while policymakers’ spending has consistently surprised to the upside
Public spending surprises relative to budget forecasts
The following analyst(s), who is(are) primarily responsible for this document, certifies(y) that the opinion(s), views or forecasts expressed herein accurately reflect their personal view(s) and that no part of their compensation was, is or will be directly or indirectly related to the specific recommendation(s) or views contained in this research report: Paul Bloxham and Jamie Culling
This document has been issued by the Research Department of HSBC.
HSBC and its affiliates will from time to time sell to and buy from customers the securities/instruments, both equity and debt (including derivatives) of companies covered in HSBC Research on a principal or agency basis or act as a market maker or liquidity provider in the securities/instruments mentioned in this report.
Analysts, economists, and strategists are paid in part by reference to the profitability of HSBC which includes investment banking, sales & trading, and principal trading revenues.
Whether, or in what time frame, an update of this analysis will be published is not determined in advance.
For disclosures in respect of any company mentioned in this report, please see the most recently published report on that company available at www.hsbcnet.com/research.
HSBC may use Artificial Intelligence (AI) tools approved for adoption within HSBC in the development of its research reports, utilizing these technologies to analyse large volumes of data, enhance efficiency and improve the overall user experience. This includes but is not limited to paraphrasing, developing suitable captions and supporting data visualisation. It is important to note that while AI tools assist in various aspects of report creation, all investment recommendations and opinions presented herein are formulated and approved exclusively by our research analysts. The final content of the report reflects the professional judgement and expertise of our research analysts, ensuring compliance with regulatory standards and maintaining the integrity of our research process.
Additional disclosures
- This report is dated as at 19 October 2026.
- All market data included in this report are dated as at close 13 October 2026, unless a different date and/or a specific time of day is indicated in the report.
- HSBC has procedures in place to identify and manage any potential conflicts of interest that arise in connection with its Research business. HSBC's analysts and its other staff who are involved in the preparation and dissemination of Research operate and have a management reporting line independent of HSBC's Investment Banking business. Information Barrier procedures are in place between the Investment Banking, Principal Trading, and Research businesses to ensure that any confidential and/or price sensitive information is handled in an appropriate manner.
- You are not permitted to use, for reference, any data in this document for the purpose of (i) determining the interest payable, or other sums due, under loan agreements or under other financial contracts or instruments, (ii) determining the price at which a financial instrument may be bought or sold or traded or redeemed, or the value of a financial instrument, and/or (iii) measuring the performance of a financial instrument or of an investment fund.
This document has been issued by HSBC Bank Australia Limited, which has based this document on information obtained from sources it believes to be reliable but which it has not independently verified. Neither HSBC Bank Australia Limited nor any member of its group companies (“HSBC”) make any guarantee, representation or warranty nor accept any responsibility or liability as to the accuracy or completeness of this document and is not responsible for errors of transmission of factual or analytical data, nor is HSBC liable for damages arising out of any person’s reliance on this information. The information and opinions contained within the report are based upon publicly available information at the time of publication, represent the present judgment of HSBC and are subject to change without notice.
This document is not and should not be construed as an offer to sell or solicitation of an offer to purchase or subscribe for any investment or other investment products mentioned in it and/or to participate in any trading strategy. It does not constitute a prospectus or other offering document. Information in this document is general and should not be construed as personal advice, given it has been prepared without taking account of the objectives, financial situation or needs of any particular investor. Accordingly, investors should, before acting on it, consider the appropriateness of the information, having regard to their objectives, financial situation and needs. If necessary, seek professional investment and tax advice.
The decision and responsibility on whether or not to purchase, subscribe or sell (as applicable) must be taken by the investor. In no event will any member of the HSBC group be liable to the recipient for any direct or indirect or any other damages of any kind arising from or in connection with reliance on any information and materials herein.
Past performance is not necessarily a guide to future performance. The value of any investment or income may go down as well as up and you may not get back the full amount invested. Where an investment is denominated in a currency other than the local currency of the recipient of the research report, changes in the exchange rates may have an adverse effect on the value, price or income of that investment. In case of investments for which there is no recognised market it may be difficult for investors to sell their investments or to obtain reliable information about its value or the extent of the risk to which it is exposed. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors.
This document is for information purposes only and may not be redistributed or passed on, directly or indirectly, to any other person, in whole or in part, for any purpose. The distribution of this document in other jurisdictions may be restricted by law, and persons into whose possession this document comes should inform themselves about, and observe, any such restrictions. By accepting this report, you agree to be bound by the foregoing instructions. If this report is received by a customer of an affiliate of HSBC, its provision to the recipient is subject to the terms of business in place between the recipient and such affiliate. The document is intended to be distributed in its entirety. Unless governing law permits otherwise, you must contact a HSBC Group member in your home jurisdiction if you wish to use HSBC Group services in effecting a transaction in any investment mentioned in this document.
Certain investment products mentioned in this document may not be eligible for sale in some states or countries, and they may not be suitable for all types of investors. Investors should consult with their HSBC representative regarding the suitability of the investment products mentioned in this document.
HSBC and/or its officers, directors and employees may have positions in any securities in companies mentioned in this document. HSBC may act as market maker or may have assumed an underwriting commitment in the securities of companies discussed in this document (or in related investments), may sell or buy securities and may also perform or seek to perform investment banking or underwriting services for or relating to those companies and may also be represented on the supervisory board or any other committee of those companies.
From time to time research analysts conduct site visits of covered issuers. HSBC policies prohibit research analysts from accepting payment or reimbursement for travel expenses from the issuer for such visits.
In Australia, this publication has been distributed by The Hongkong and Shanghai Banking Corporation Limited (ABN 65 117 925 970, AFSL 301737) for the general information of its “wholesale” customers (as defined in the Corporations Act 2001). Where distributed to retail customers, this research is distributed by HSBC Bank Australia Limited (ABN 48 006 434 162 AFSL No. 232595).
Should you wish to use AI technology (computational, statistical, machine-learning or other artificial intelligence techniques to infer or learn from data to find patterns, take actions, make decisions, or generate output) to help you analyse, summarise or evaluate this publication and/or any other research materials provided to you by HSBC, you shall seek HSBC consent in advance of any such use and not upload this publication and/or any other research materials produced by HSBC to an AI system or otherwise use AI technology in connection with the research services HSBC provides to you without our consent.
© Copyright 2026, HSBC Bank Australia Limited, ALL RIGHTS RESERVED. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the issuer of the report.